

Best CD Rates in 2026


QUICK PICKS
- Best overall: E*TRADE CD pays 4.55% APY on its 12-month term and 4.80% on 24 to 60 months, with no minimum deposit.
- Best for a five-year term: Sallie Mae CDs pays 5.00% APY on its 60-month CD once you deposit $2,500.
- Best for an 18-month term: Bread Savings CD pays 4.85% APY, the highest 18-month rate in this guide.
Rates verified October 26, 2026. A CD's APY is fixed once you fund it.
Term length, APY, and minimum deposit decide which CD pays the best CD rates for you, and E*TRADE CD tops our list with a 4.55% APY on its 12-month term and no minimum deposit. Sallie Mae CD and Bread Savings CD pay more on longer terms, while Marcus High-Yield CD and Synchrony CD offer flexibility on term length and deposit size.
We scored each CD out of 5 on rate value (40%), fees and transparency (25%), eligibility and access (20%), and support and reviews (15%), using figures from each bank’s own website verified on October 26, 2026. A CD’s rate stays fixed after you fund it, yet the advertised APY can change before then, so confirm it before you open the account.
Jump to:
Best CD Rates: Top 5 Compared
Use this table to compare the best CD rates and each high yield CD account side by side on 12-month APY, top APY by term, and the deposit each bank requires to earn it.
|
CD |
Best for |
12-month APY |
Highest APY (term) |
Minimum to earn APY |
FDIC insurance |
|---|---|---|---|---|---|
 |
Top 12-month rate with no minimum |
4.55% |
4.80% (24, 36, and 60 months) |
$0 |
Up to $250,000 per depositor, and up to $500,000 for qualifying joint accounts |
 |
60-month terms |
4.50% |
5.00% (60 months) |
$2,500 |
Up to $250,000 per depositor, per ownership category |
 |
18-month terms |
4.45% |
4.85% (18 months) |
$1,500 |
Up to $250,000 per depositor, per ownership category |
 |
Steady rate on long terms |
4.40% |
4.40% (12 months to 6 years) |
$500 |
Up to $250,000 per depositor, per ownership category |
 |
Flexible terms with no minimum |
4.20% |
4.50% (60 months) |
$0 |
Up to $250,000 per depositor, per ownership category |
All five 12-month APYs fall within 0.35 percentage points of each other, so your minimum deposit and preferred term often decide the winner. CD account rates also shift with term length: Sallie Mae CDs pays 5.00% at 60 months, while Bread Savings CD peaks at 4.85% on 18 months.
The Best CD Rates, Reviewed
Each review lists the verified APYs, fees, and withdrawal rules behind our score, with the picks ranked from highest to lowest.
1. E*TRADE CD [Best for Top 12-Month Rate With No Minimum]
E*TRADE CD pays 4.55% APY on its 12-month term and 4.80% APY on 24-, 36-, and 60-month terms, the highest 12-month rate we verified, with no minimum deposit and no monthly fees. It takes the top spot because it pairs the strongest one-year rate with the lowest barrier to entry.
Verified terms for E*TRADE CD:
E*TRADE CD
CD Details
- Minimum deposit
- $0
- Monthly fees
- None
- 12-month APY
- 4.55%
- Highest APY
- 4.80% on 24-, 36-, and 60-month terms
- Other APYs
- 6 months: 4.20%; 9 months: 4.40%; 18 months: 4.55%
- Early withdrawal penalty
- Days of simple interest, set by term; the principal is also penalized if the penalty exceeds accrued interest
- Grace period
- 7 calendar days after maturity
- Renewal
- Automatic at maturity
- Insurance
- FDIC, through Morgan Stanley Private Bank, National Association
- Other perks
- Fixed APY, daily compounding, 10-day rate guarantee lets you automatically get the higher of the rate from either the day you opened or the day your deposit settles.
- Last verified
- October 26, 2026
A $5,000 deposit at 4.55% for 12 months earns $227.50. The 18-month term pays the same 4.55%, so the extra six months add no rate, while CD account rates at E*TRADE climb to 4.80% from 24 months. E*TRADE sets the early withdrawal penalty as a number of days of simple interest that depends on your term, and a 7-day grace period follows maturity. If you do nothing at maturity, the CD renews automatically.
Trustpilot reviewers rate E*TRADE 1.1 out of 5, which pulled down its support and reviews score. Read recent customer feedback before you fund the account.
|
Pros |
Cons |
|---|---|
|
✅ 4.55% APY on the 12-month term, the highest we verified. ✅ No minimum deposit and no monthly fees. ✅ 4.80% APY on 24-, 36-, and 60-month terms. |
❌ An early withdrawal penalty applies and can reach principal. ❌ The CD renews automatically at maturity. |
Open E*TRADE CD, our best CD account for a strong 12-month rate without a deposit requirement. If you can leave $2,500 or more untouched for five years, compare it with Sallie Mae CDs, which pays 5.00% on its 60-month term.
2. Sallie Mae CDs [Best for 60-Month Terms]
Sallie Mae CDs pay 4.50% APY on terms from 12 to 30 months and 5.00% APY on the 60-month term, the highest long-term rate among the best CD rates in this comparison. The bank asks for $2,500 to open the CD and to keep earning interest, and its CD account rates are the highest among the best CD rates in this guide on long terms.
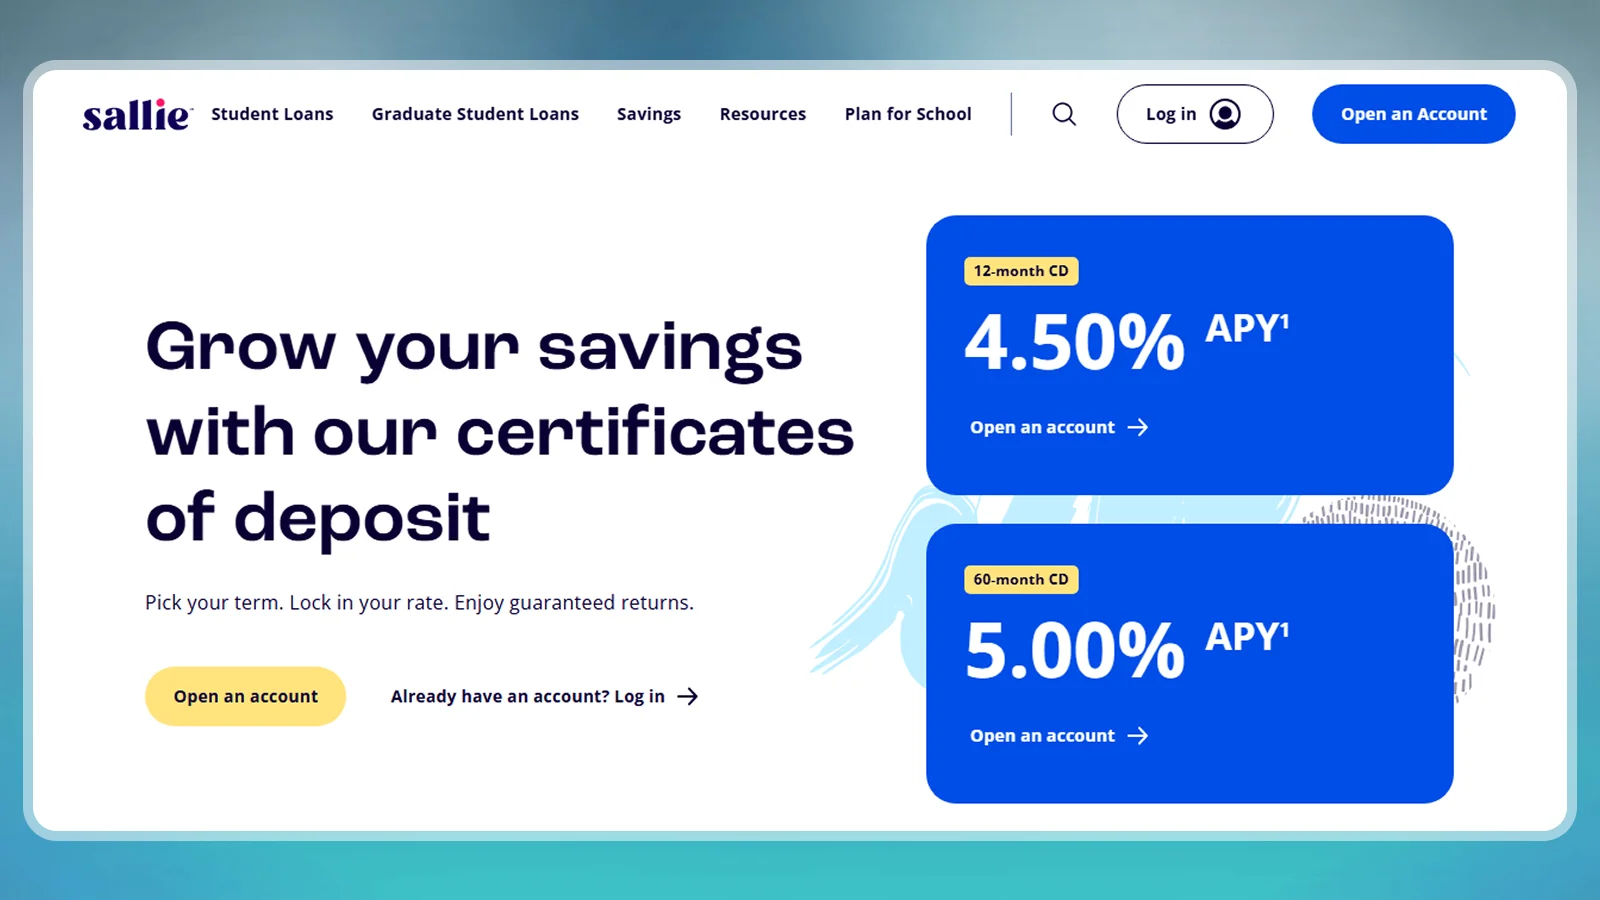
The table below summarizes the terms we verified for Sallie Mae CDs.
Sallie Mae CDs
CD Details
- Minimum to open and earn
- $2,500
- Monthly fees
- None
- 12-month APY
- 4.50%
- Highest APY
- 5.00% on the 60-month term
- Other APYs
- 6 months: 3.20%; 11 months: 4.10%; 36 months: 4.60%
- Early withdrawal penalty
- 90 days of simple interest on terms of 12 months or less; 180 days on longer terms; the penalty can reach principal
- Insurance
- FDIC: $250,000 per co-owner, up to $500,000 for qualifying joint accounts
- Other perks
- Locked-in rates, automatic renewal
- Last verified
- October 26, 2026
A $10,000 deposit at 5.00% for 60 months grows by about $2,763, because the APY compounds each year. The 180-day penalty on terms over 12 months can exceed the interest you have earned and then reach your principal, so commit only money you can leave alone. Joint accounts that meet FDIC ownership rules can carry up to $500,000 of coverage.
The $2,500 minimum is the highest of the five CDs here, and a balance below it stops earning interest.
|
Pros |
Cons |
|---|---|
|
✅ 5.00% APY on the 60-month term. ✅ 4.50% APY on terms from 12 to 30 months. ✅ Joint accounts can carry up to $500,000 of FDIC coverage. |
❌ $2,500 minimum to open and keep earning, the highest of the five. ❌ A 180-day penalty applies on terms over 12 months and can reach principal. |
Choose Sallie Mae CDswhen you have $2,500 or more and want to fix a rate for several years, which makes it the best CD account here for five-year savers. With a smaller deposit, E*TRADE CD and Synchrony CD both accept any amount.
3. Bread Savings CD [Best for 18-Month Terms]
Bread Savings CD pays 4.85% APY on its 18-month term, the highest 18-month rate among the best CD rates we checked, and 4.45% on a 1-year term. Each CD needs a $1,500 opening deposit and carries no monthly maintenance fee.
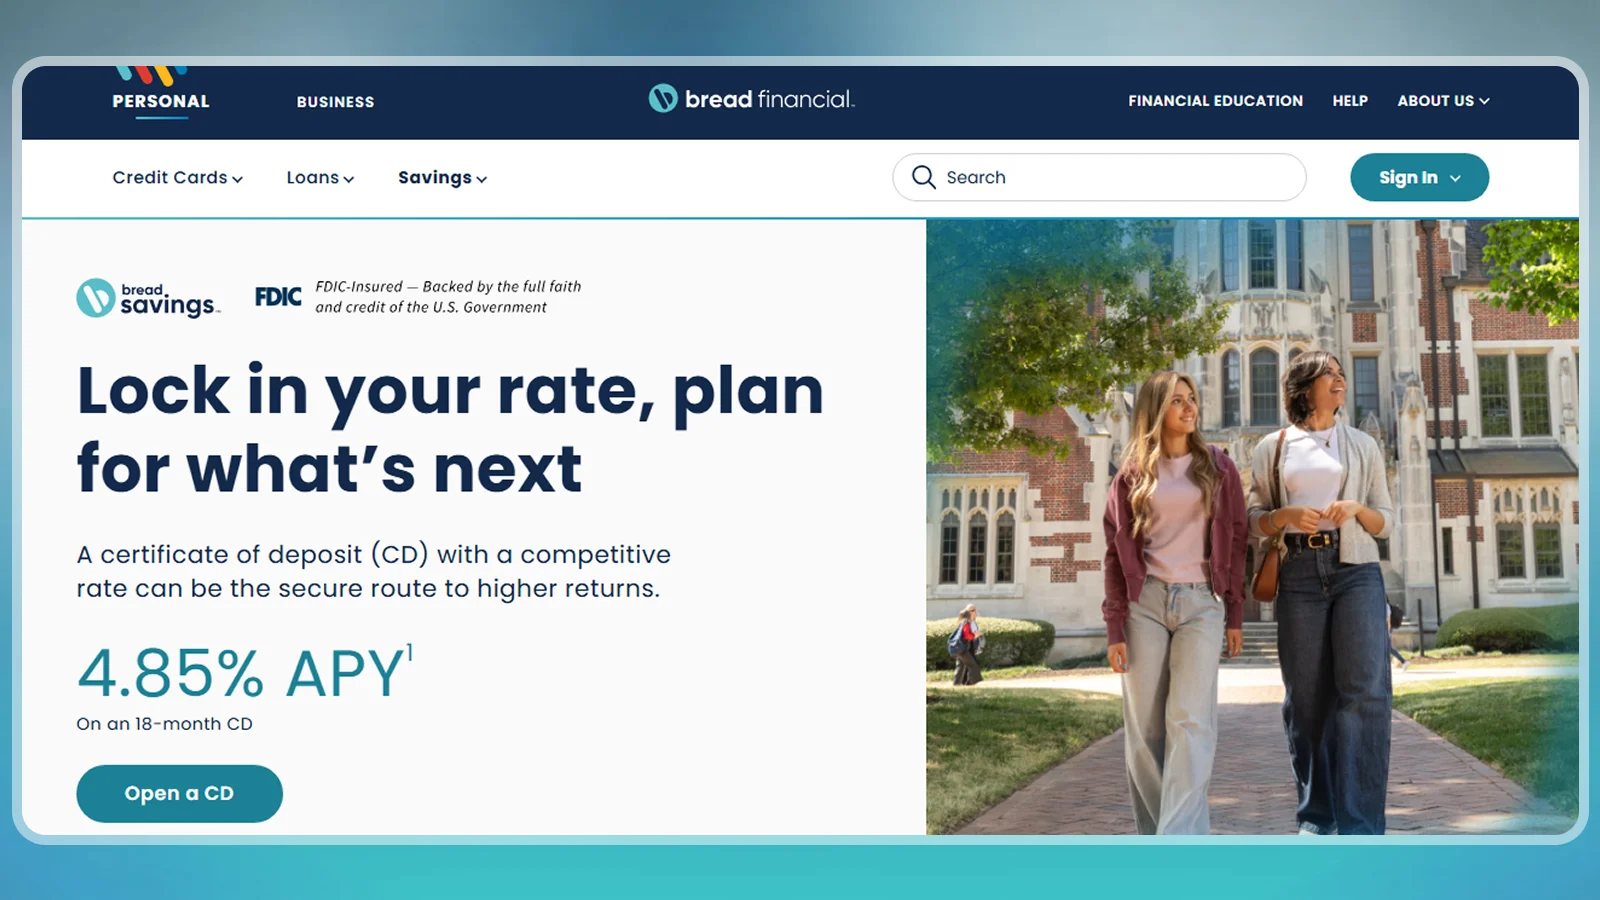
Here is what we verified on the Bread Savings page.
Bread Savings CD
CD Details
- Minimum deposit
- $1,500, deposited in a single transaction
- Maximum deposit
- $1,000,000 per account
- Monthly fees
- No monthly maintenance fee
- 12-month APY
- 4.45%
- Highest APY
- 4.85% on the 18-month term
- Other APYs
- 3 months: 3.95%; 6 months: 4.05%; 2 years: 4.55%; 5 years: 4.70%
- Early withdrawal penalty
- 90 days of simple interest on terms under 12 months; 180 days for 12 months to 3 years; 365 days for 4 years and up
- Renewal
- Automatic at maturity, at the base rate in effect at that time
- Insurance
- FDIC, through Comenity Capital Bank: $250,000 per depositor, per ownership category
- Other perks
- Automatic renewal, 10 calendar days to withdraw the funds or close the account without penalty
- Last verified
- October 26, 2026
On $5,000, 4.85% APY over 18 months earns about $368. The CD compounds interest daily and posts it monthly. At maturity it renews at the base rate in effect then, so set a reminder before the end date. Among CD account rates here, its 5-year APY of 4.70% trails the 5.00% at Sallie Mae CD.
The penalty climbs to 365 days of simple interest on terms of four years and longer, so match the term to money you can leave alone.
|
Pros |
Cons |
|---|---|
|
✅ 4.85% APY on the 18-month term, the highest 18-month rate here. ✅ No monthly maintenance fee. ✅ Terms from 3 months to 5 years. |
❌ $1,500 minimum opening deposit. ❌ The CD renews at the base rate in effect at maturity. |
Bread Savings CDworks as a high yield CD account for money you can park for a year and a half. If $1,500 is more than you want to commit, E*TRADE CD starts at $0.
4. Marcus High-Yield CD [Best for Steady Rates on Long Terms]
Marcus High-Yield CD pays 4.40% APY on every term from 12 months to 6 years, so you can extend your term without taking a lower rate. The CD requires $500 to open and to earn the stated APY.
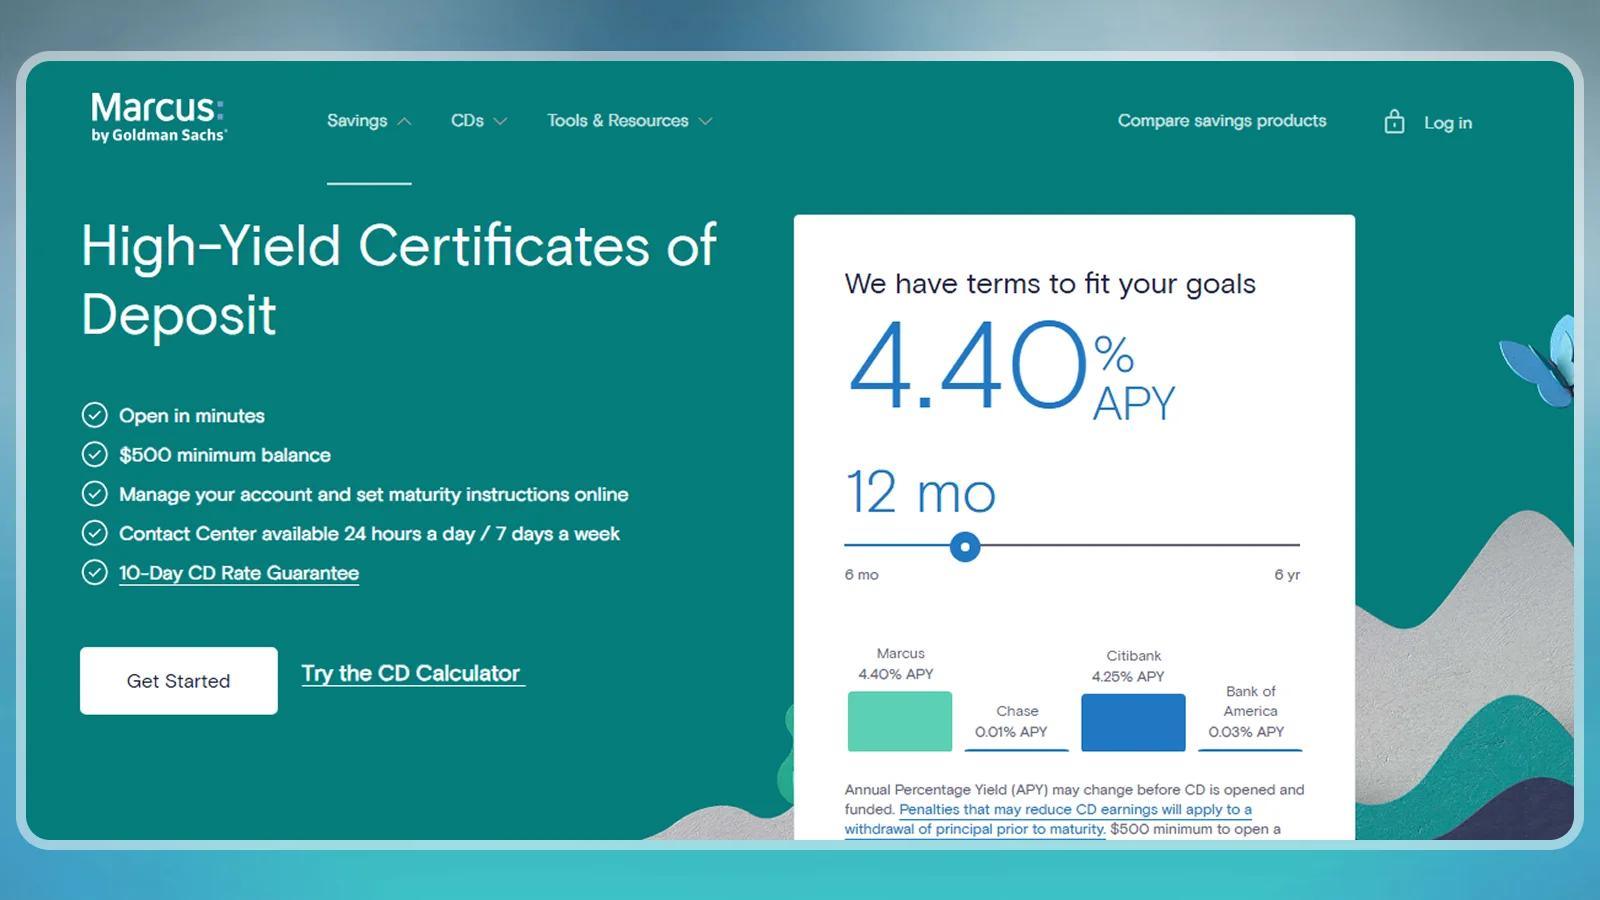
Marcus High-Yield CD at a glance:
Marcus High-Yield CD
CD Details
- Minimum to open and earn
- $500
- Maximum balance
- $1,000,000 per account
- 12-month APY
- 4.40%
- Highest APY
- 4.40% on terms from 12 months to 6 years
- Other APYs
- 6 months: 3.95%; 9 months: 4.30%
- Early withdrawal penalty
- Applies; depositors can calculate the amount using the Early Withdrawal Penalty Calculator in their Account Details page
- Support
- Chat and phone, 24/7
- Insurance
- FDIC, through Goldman Sachs Bank USA
- Other perks
- 10-day CD rate guarantee lets you receive the higher rate if the rate on your term rises within 10 days and you deposit at least $500 in that window
- Last verified
- October 26, 2026
Because its CD account rates are the same from 12 months to 6 years, your term depends on how long you can leave the money alone. A longer term keeps the 4.40% rate in place after rates elsewhere fall, while a 12-month CD frees your cash sooner. The bank also lists maximum balance limits, and the early withdrawal penalty amounts appear on a separate page.
Check the penalty page before you choose a long term, because the product page names no early withdrawal amounts.
|
Pros |
Cons |
|---|---|
|
✅ 4.40% APY on every term from 12 months to 6 years. ✅ $500 minimum to open and earn. ✅ A higher rate applies automatically if your term rises in the first 10 days and you deposit at least $500. |
❌ Early withdrawal penalty amounts sit on a separate page. ❌ Maximum balance limits apply. |
Marcus High-Yield CDfits savers who want the option to extend a term without a rate drop. For the top 12-month APY among the best CD rates, choose E*TRADE CD at 4.55%. Marcus also works as a high yield CD account for longer commitments.
5. Synchrony CD [Best for Flexible Terms With No Minimum]
Synchrony CD requires no minimum deposit and no minimum balance and pays 4.20% APY on its 12-month term, rising to 4.50% on the 60-month term. It also sells terms such as 13 months, which pays 4.40%.
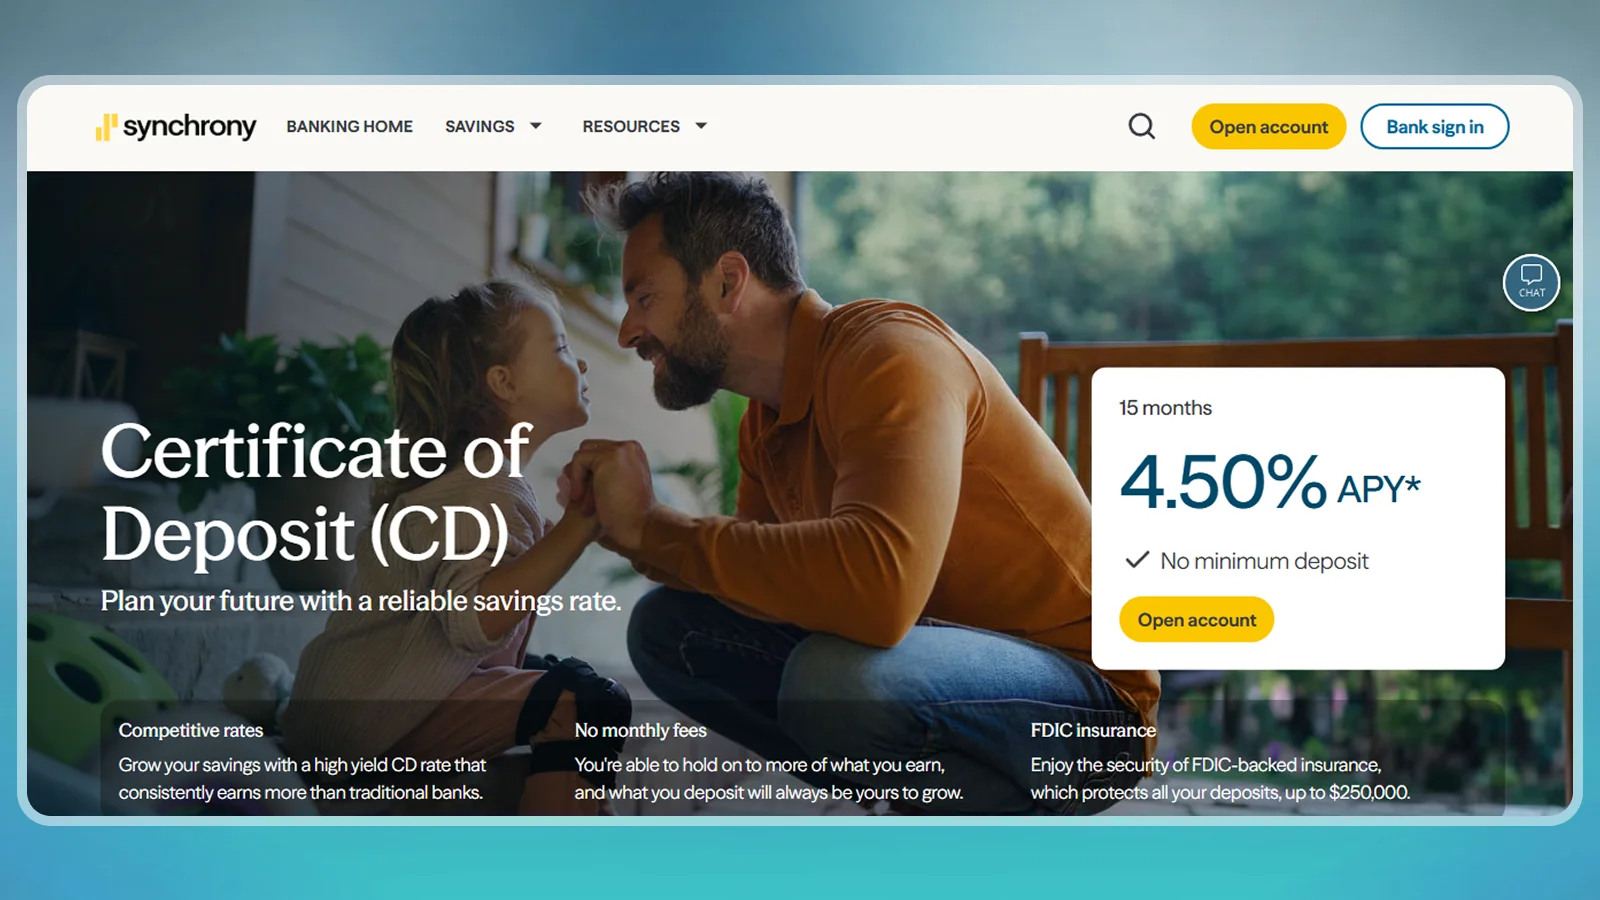
The terms we verified for Synchrony CD appear below.
Synchrony CD
CD Details
- Minimum deposit
- None
- Minimum balance
- None
- 12-month APY
- 4.20%
- Highest APY
- 4.50% on the 60-month term
- Other APYs
- 6 months: 4.10%; 9 months: 4.15%; 18 and 24 months: 4.35%; 36 and 48 months: 4.40%
- Early withdrawal penalty
- 90 days of simple interest on terms of 12 months or less; 180 days on terms over 12 and under 48 months; 365 days on terms of 48 months or more
- Insurance
- FDIC, up to $250,000 per depositor, per ownership category
- Other perks
- Bump-Up CD rise lets you request a rate increase once during the term of the CD
- Last verified
- October 26, 2026
Among Synchrony CD account rates, the 13-month CD pays 4.40%, which sits 0.20 points above the 12-month rate, so one extra month adds yield. On $5,000, the 12-month term earns $210 and the 13-month term earns about $239. Penalty tiers are spelled out by term length, which makes the cost of a withdrawal easy to estimate.
The 12-month APY is the lowest of the five best CD rates in this guide, so compare it with E*TRADE CD before you choose a one-year term.
|
Pros |
Cons |
|---|---|
|
✅ No minimum deposit or minimum balance. ✅ 4.40% APY on the 13-month term, 0.20 points above 12 months. ✅ Penalty tiers listed by term. |
❌ The 12-month APY of 4.20% is the lowest of the five. ❌ The penalty reaches 365 days of simple interest on terms of 48 months or more. |
Pick Synchrony CDas a high yield CD account that accepts any amount, with a term such as 13 months. For a higher 12-month rate at the same $0 minimum, E*TRADE CD pays 0.35 points more.
E*TRADE CD vs. Sallie Mae CD: Which Pays More?
The two highest-ranked picks among the best CD rates sit only 0.05 points apart on a 12-month term, at 4.55% for E*TRADE CD and 4.50% for Sallie Mae CD. Term length and deposit size separate them: E*TRADE CD pays more up to 36 months and needs no minimum, while Sallie Mae CD pays 5.00% at 60 months against 4.80%.
|
CD detail |
E*TRADE CD |
Sallie Mae CD |
|---|---|---|
|
12-month APY |
4.55% |
4.50% |
|
36-month APY |
4.80% |
4.60% |
|
60-month APY |
4.80% |
5.00% |
|
Minimum to earn APY |
$0 |
$2,500 |
|
Monthly fees |
None |
None |
|
Early withdrawal penalty |
Days of simple interest, set by term |
90 or 180 days of simple interest |
|
Our score |
4.3 out of 5 |
4.2 out of 5 |
Pick E*TRADE CD for terms of 12 to 36 months or any deposit under $2,500. Pick Sallie Mae CD for a 60-month term with $2,500 or more. Comparing the best CD rates term by term shows where each bank leads and helps you find the best CD account for your term.
How Much Can You Earn With a CD Account?
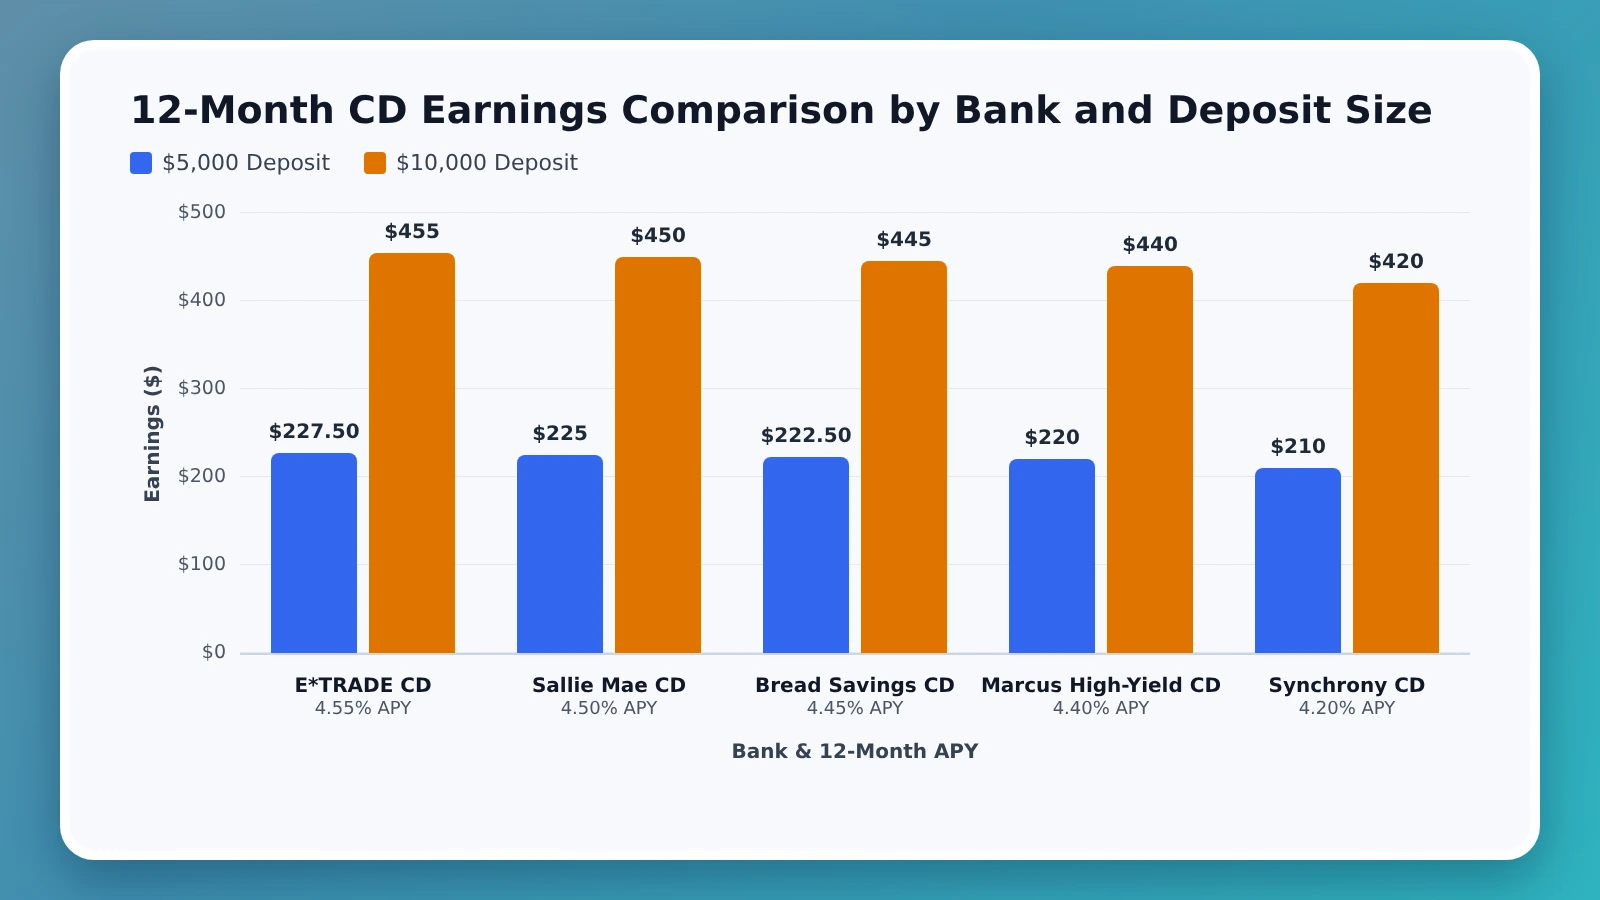
A $10,000 deposit in E*TRADE CD for 12 months earns $455 at 4.55% APY, compared with $420 at Synchrony CD, a $35 gap on the same deposit. The table applies each bank’s 12-month APY to two deposit sizes, held to maturity with no withdrawals.
| CD | 12-month APY | Earnings on $5,000 | Earnings on $10,000 |
| E*TRADE CD | 4.55% | $227.50 | $455 |
| Sallie Mae CD | 4.50% | $225 | $450 |
| Bread Savings CD | 4.45% | $222.50 | $445 |
| Marcus High-Yield CD | 4.40% | $220 | $440 |
| Synchrony CD | 4.20% | $210 | $420 |
APY already includes compounding, so each figure equals the deposit times the APY for a full year. Longer terms change the picture: $10,000 in Sallie Mae CD at 5.00% for 60 months earns about $2,763. These examples assume the APY stays the same through maturity, which holds only if you open the CD at the rate shown, so check the live rate first.
What Is a CD Account?
A CD, or certificate of deposit, is a fixed-term deposit account that pays a set interest rate in exchange for leaving your money untouched until maturity. When you open a CD account, you pick a term, from a few months to several years, and the bank fixes your APY for that period.
Learning how a CD account works comes first, because it explains why the best CD rates vary so much by term. A high yield CD account is a CD that pays a top-tier APY for its term, and all five picks here carry FDIC insurance up to $250,000 per depositor, per ownership category.
Certificate of Deposit vs High-Yield Savings
A high-yield savings account pays a variable APY, so your bank can raise or lower the rate at any time. You can deposit and withdraw whenever you like, which keeps your cash accessible. A CD locks in one rate for the full term, and taking money out early usually costs an early withdrawal penalty.
If you want to keep your cash liquid, see our guide to the best banks for high yield savings account.
|
Feature |
CD account |
High yield savings account |
|---|---|---|
|
Rate |
Fixed for the term |
Variable; the bank can change it |
|
Access to funds |
Locked until maturity, with a penalty for early withdrawal |
Withdraw anytime, within the bank’s limits |
|
Best for |
Money you won’t need for a set period |
An emergency fund or flexible savings |
How to Open a CD Account
Opening a CD account online usually takes about 10 to 15 minutes. These steps apply to every bank on our best CD rates list, though funding rules differ.
- Compare APYs for the term you want, then choose the CD that fits your deposit and timeline.
- Gather your Social Security number and a government-issued ID, which banks commonly request. Each bank lists its own eligibility rules.
- Apply on the bank’s website and select your term.
- Fund the CD by electronic transfer. The minimum is $0 at E*TRADE CD and Synchrony CD, $500 at Marcus High-Yield CD, $1,500 at Bread Savings CD, and $2,500 at Sallie Mae CD.
- Record your maturity date and the bank’s grace period, such as the 7 days E*TRADE allows after maturity, so you can withdraw or renew on time.
Choosing the Best CD Account for You
Your deposit size and how long you can leave the money alone narrow the field quickly. Match your situation below to find the best CD account for your goal:
- You have less than $1,500 to start: E*TRADE CD and Synchrony CD both accept any amount.
- You want the top 12-month APY: E*TRADE CD pays 4.55%, the highest of the best CD rates for one year.
- You can commit for five years with $2,500 or more: Sallie Mae CD pays 5.00%.
- You can commit for 18 months: Bread Savings CD pays 4.85%.
- You want one rate across long terms: Marcus High-Yield CD pays 4.40% from 12 months to 6 years.
Two CDs from earlier lineups missed the top five on 12-month APY. Capital One 360 CD has no minimum or monthly fee and pays 4.40% on an 11-month term (a limited-time offer), but only 4.00% at 12 months. American Express High Yield CD also has no minimum or monthly fee and pays 4.40% on 10- and 22-month terms, yet 3.65% at 12 months. Both remain a high yield CD account option if their specific terms fit your plan.
Check each bank’s page for age, residency, and ID requirements before you apply. To compare CDs with other deposit products, check out the best money market accounts.
Final Verdict on the Best CD Rates
E*TRADE CD is the best CD account for most savers today, with 4.55% APY on a 12-month term, 4.80% on terms of 24 to 60 months, and no minimum deposit. Sallie Mae CD takes over for five-year terms at 5.00%, and Bread Savings CD leads at 18 months with 4.85%. Advertised rates can change before you fund an account, so confirm the live APY on the bank’s site before you commit.
FAQs
A CD fixes your APY for the full term, so it protects you if rates fall. That makes it a good fit for money you will not need before maturity, since taking it out early usually costs a penalty.
Banks can change their advertised APYs at any time, but a CD you already opened keeps its rate until maturity. We recheck our picks every 30 days, so confirm the current rate on the bank’s site before you open one.
Yes. CDs at FDIC-insured banks are covered up to $250,000 per depositor, per ownership category. Sallie Mae CDs notes that a qualifying joint account can raise that coverage to as much as $500,000, and four of the five accounts in this comparison confirm FDIC insurance.
No. Opening a cd account is a deposit, not a loan, so credit checks typically aren’t part of the process. Issuers typically verify your identity with a Social Security number and a government-issued ID instead of checking your credit score or income.
It depends whether the best cd rates matter more than liquidity for your situation. A cd account locks in a fixed rate for a set term, such as Sallie Mae CDs‘s 4.30% APY over 12 months. A high yield savings account instead keeps your funds liquid, paying a variable rate that can rise or fall at any time.
An early withdrawal penalty applies. Marcus High-Yield CD, Sallie Mae CD, and Capital One 360 CD all state penalties for withdrawing before maturity. The penalty usually costs several months of interest, so leave the money untouched to earn the best CD rates for the full term.